HMA
Source
https://github.com/quadcode-tech/quadcodescript-library/blob/master/averages/ma_hma.lua
Syntax Format
hma(series, period)
Overview
HMA (Hull Moving Average) belongs to the MA family, and aims at smoothing the asset price movements. HMA might have more advantages compared to SMA and EMA in regard to being more responsive to the price changes.
The function returns the Hull moving average of source for the period bars.
Parameters
| Parameter | Type | Purpose |
|---|---|---|
| series | series | Input series, taken into calculation |
| period | numeric | MA (moving average) period |
Returns: series.
Example
instrument { name = "Hull Moving Average", short_name = "HMA", overlay = true, icon="indicators:MA" }

period = input (9, "period", input.integer, 1)
source = input (1, "source", input.string_selection, inputs.titles_overlay)

input_group {
    "HMA Line",
    color = input { default = "#B42EFF", type = input.color },
    width = input { default = 1, type = input.line_width}
}

local sourceSeries = inputs [source]

plot (hma (sourceSeries, period), "HMA", color, width)
Formula
The formula for calculating HMA is:
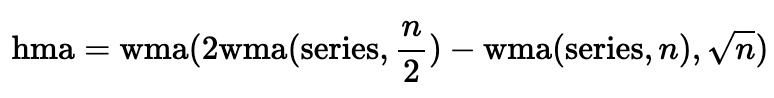
The Weighted Moving Average values are used for the calculation: first, half of the period is calculated, then the full period value is calculated. Then, the second WMA value is subtracted from the first one, the final step applies a WMA with a period of √n to the result.